Contents:
- Direct Answer
- Why This Is So
- Detailed Breakdown
- Regional Difference
- Sustainability Angle
- Exceptions and Nuances
- FAQ
- How long does it take to build solid business credit?
- Do all vendors report payment history to business credit bureaus?
- Can I build business credit without using personal credit at all?
- Wrap-Up
- Personal Anecdote
- Common Mistakes to Avoid
Picture opening your first business bank account, feeling accomplished, and then discovering months later that lenders still won’t look past your personal credit score because your business essentially has no financial history of its own yet.
Direct Answer
Building small business credit requires establishing your business as a separate legal and financial entity, then deliberately using and repaying business credit accounts to create a track record that lenders and suppliers can evaluate independently of your personal credit.
Why This Is So
Business credit exists separately from personal credit because lenders and vendors need a way to assess a company’s specific reliability, and building this history early protects your personal credit while unlocking better business financing terms over time.
Detailed Breakdown
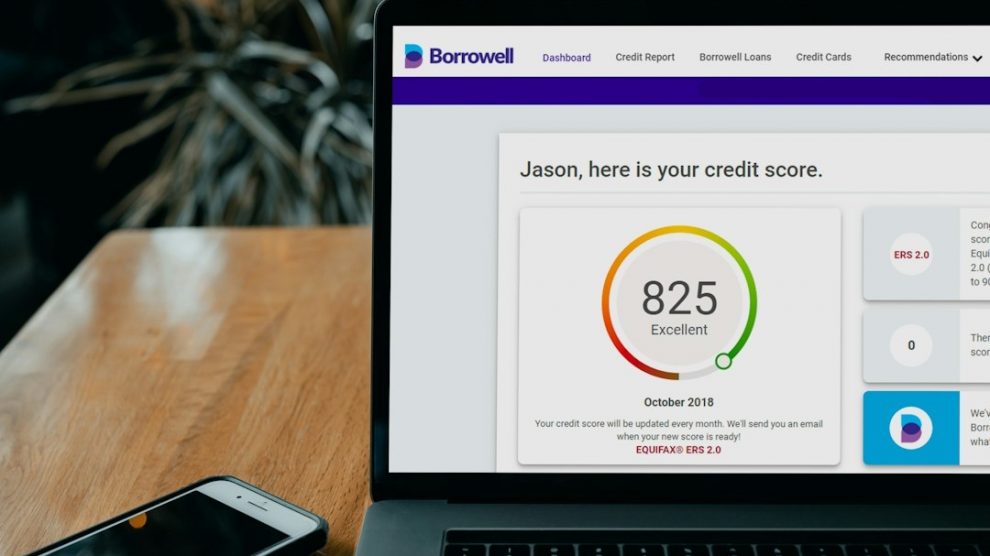
Start by obtaining an EIN and opening a dedicated business bank account, since these establish your business as a distinct entity in the eyes of credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Business.
Next, open trade credit accounts with suppliers who report payment history to business credit bureaus, then apply for a business credit card, using it regularly and paying balances in full to build positive payment history.
Register with Dun & Bradstreet to obtain a D-U-N-S Number, since many lenders and larger vendors specifically check this identifier before extending business credit or favorable payment terms.
Regional Difference
Businesses in the Northeast often work with community banks and credit unions that weigh local relationships heavily, while West Coast tech-adjacent businesses frequently rely more on online lenders and fintech credit-building tools suited to newer companies.
Sustainability Angle
Some business credit card issuers now offer green rewards programs, giving cash back or credits toward sustainable business investments like solar equipment or energy-efficient upgrades as you build your credit history.
Exceptions and Nuances
Sole proprietors face a genuine limitation, since business and personal credit remain more intertwined without a formal LLC or corporation structure separating the two financial identities completely.
FAQ
How long does it take to build solid business credit?
Most businesses see meaningful business credit scores develop within six to twelve months of consistent, on-time payment activity across multiple reporting accounts and vendors.
Do all vendors report payment history to business credit bureaus?
No, ask specifically whether a supplier reports to Dun & Bradstreet or other bureaus, since not reporting means on-time payments won’t help build your credit profile.
Can I build business credit without using personal credit at all?
Eventually yes, but early on, most new businesses need at least some personal credit backing until sufficient independent business credit history accumulates over time.
Wrap-Up
Deliberately building business credit through proper entity setup, trade accounts, and consistent repayment creates long-term financing flexibility that protects your personal finances as your business grows.
Personal Anecdote
A first-time bakery owner in Cleveland spent nearly a year using only a personal credit card for supply purchases, then discovered when applying for an equipment loan that lenders wanted to see genuine business credit history rather than her personal utilization, forcing her to restart the entire building process months later than necessary.
Common Mistakes to Avoid
Applying for too many trade accounts and credit lines within a short window can actually hurt your emerging business credit profile, since multiple simultaneous inquiries signal risk to lenders reviewing your file.